COMMENTARY:
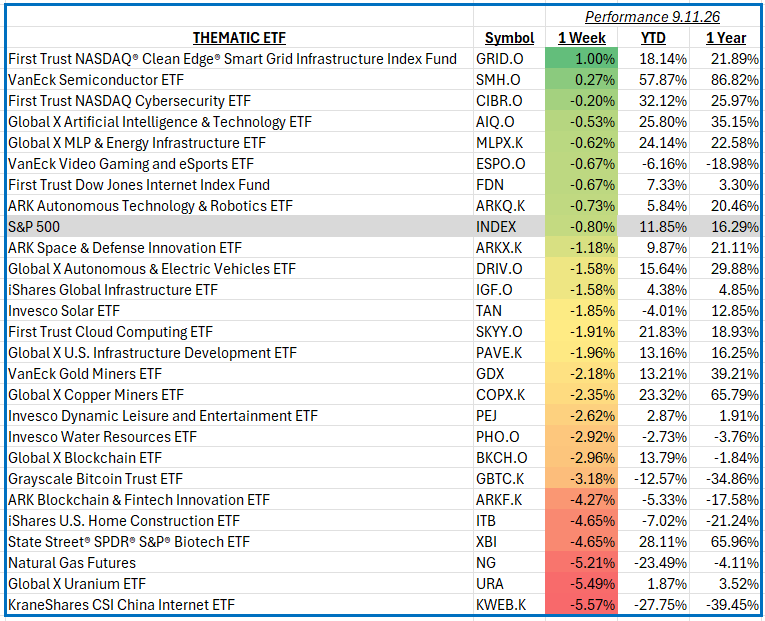
The S&P 500 declined 0.80% for the week as investors balanced persistent inflation pressures, rising oil prices and higher Treasury yields against continued strength in select growth themes. August CPI increased 0.4% month over month and 3.4% year over year, reinforcing expectations for a potentially more restrictive Federal Reserve. At the same time, geopolitical tensions surrounding the Strait of Hormuz pushed oil sharply higher before prices retreated Friday on reports of diplomatic efforts.
AI Power & Grid Infrastructure was the strongest thematic area, led by Smart Grid & Electrification, which gained 1.00% and outperformed the S&P 500 by 1.80 percentage points—the largest positive difference among the highlighted themes. Eaton, Quanta Services, GE Vernova and Hubbell benefited from continued expectations for significant electricity and transmission investment associated with data-center growth. Investors increasingly appear to favor companies monetizing AI-related power demand today rather than relying solely on future technology adoption.
Semiconductors & Cybersecurity also proved relatively resilient. Semiconductors gained 0.27%, while cybersecurity declined only 0.20%, both substantially better than the broader market. Nvidia, Broadcom, AMD and Taiwan Semiconductor helped support semiconductor performance as AI infrastructure spending remained a dominant investment narrative. Within cybersecurity, Palo Alto Networks, CrowdStrike, Fortinet and Cisco provided relative stability. Semiconductor stocks also rallied strongly Friday as falling oil prices eased some inflation concerns.
Uranium & Nuclear Energy was one of the weakest thematic groups, with uranium investments falling 5.49%. Cameco, Uranium Energy and NexGen Energy were among the important companies influencing the group. Despite the long-term investment case for nuclear power and growing electricity demand, higher interest rates and a shift away from more speculative, future-oriented investments weighed on uranium-related equities. Nuclear power remains an important component of the broader AI electricity theme, but investors were more selective this week.
China Internet & Digital Assets also faced significant pressure. China Internet investments declined 5.57%, 4.77 percentage points below the S&P 500 and 0.08 percentage points worse than uranium. Alibaba, Tencent, JD.com and Meituan were among the key contributors to weakness as investors reduced exposure to international growth themes amid a stronger U.S. dollar and broader risk aversion. Blockchain and digital-asset investments were similarly volatile as Bitcoin weakened during the week, pressuring companies such as Coinbase and major crypto miners.
Overall, thematic investing remained highly selective this week: investors favored tangible beneficiaries of AI infrastructure and power demand while reducing exposure to higher-duration and more speculative themes.
