COMMENTARY:
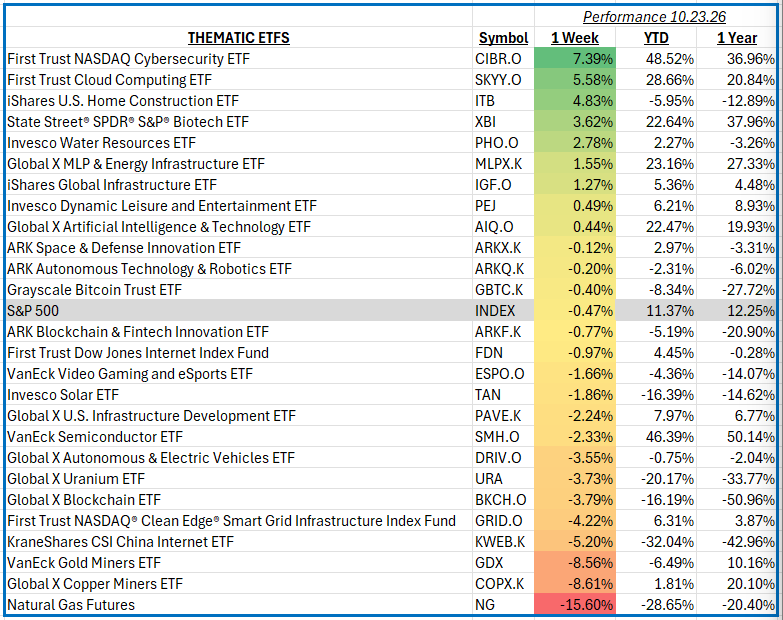
The S&P 500 declined 0.47% for the week ending October 23, 2026, as investors reassessed the costs and potential returns of artificial intelligence (AI) investments. Despite several strong corporate earnings reports, rising capital expenditure forecasts pressured technology shares. Meanwhile, escalating Middle East tensions pushed oil prices higher, renewing inflation concerns. Investors also monitored Treasury yields and prepared for the Federal Reserve’s upcoming policy decision. Performance varied considerably across thematic investments, with cybersecurity and cloud computing gaining while semiconductor-related and commodity investments faced pressure.
Cybersecurity and Cloud Computing
Cybersecurity led the thematic investment landscape, advancing 7.39% as demand for digital security solutions remained resilient. Zscaler, Okta, CrowdStrike, and Palo Alto Networks posted notable gains, reflecting investor interest in protecting increasingly complex digital infrastructure. Cloud computing rose 5.58%, supported by strength in enterprise software and cloud-service providers. SAP benefited from robust cloud growth, while investors continued evaluating the commercial opportunities associated with AI infrastructure. Despite concerns about AI spending, cybersecurity and software companies demonstrated that opportunities remain across technology beyond semiconductor manufacturing.
Housing and Infrastructure
Home construction gained 4.83%, supported by improving investor interest in housing-related businesses. Builders such as D.R. Horton, Lennar, and PulteGroup remained important companies to watch as mortgage affordability, construction costs, and housing demand influenced the industry’s outlook. Infrastructure investments also attracted attention as investors assessed long-term spending opportunities in transportation, utilities, and electrical equipment. However, weaker housing activity and uncertainty surrounding interest rates remained potential challenges for residential construction.
Semiconductors, AI, and Digital Innovation
AI-related investments experienced a more difficult week as investors questioned whether enormous infrastructure expenditures would generate sufficient returns. Meta Platforms fell after increasing its capital-spending outlook, while semiconductor companies including Lam Research and Nvidia faced pressure amid concerns about financing and sustaining AI infrastructure growth. Robotics, autonomous vehicles, digital advertising, gaming, and fintech investments also faced an uncertain environment as investors distinguished between near-term profitability and longer-term growth opportunities.
Commodities, Energy, and Natural Resources
Copper mining declined 8.61%, underperforming the S&P 500 by 8.14 percentage points and reflecting weakness across metals-related investments. Gold mining also struggled as gold prices retreated, weighing on producers such as Newmont and Barrick Mining. Natural gas futures fell 15.60%, underperforming copper mining by 6.99 percentage points, as prices remained under pressure. Meanwhile, geopolitical tensions supported crude oil prices, illustrating the divergent performance across energy commodities.
Closing Thoughts: Thematic investing delivered mixed results, with cybersecurity, cloud computing, and housing outperforming while commodities and AI hardware struggled. Investors will watch corporate earnings, the Federal Reserve, and economic data for signals about growth and future investment opportunities.