COMMENTARY:
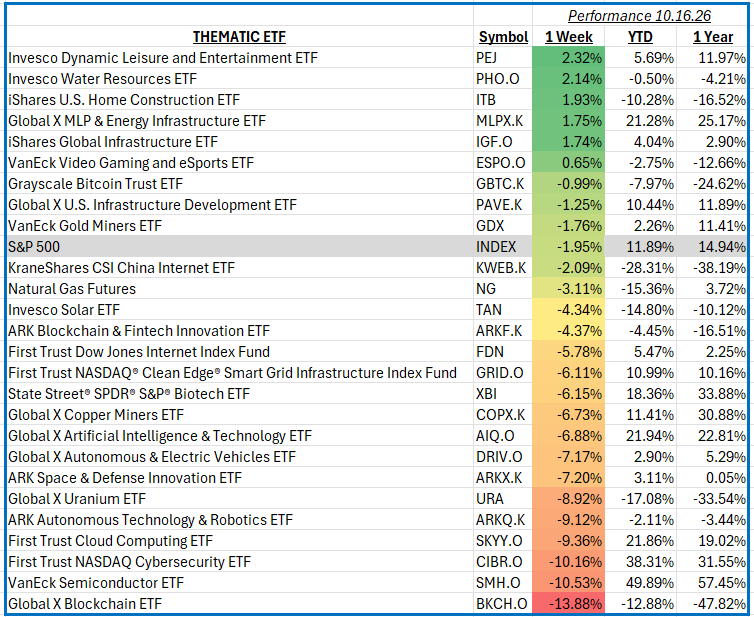
The S&P 500 declined 1.95% for the week ending October 16, as investors reassessed technology valuations, artificial intelligence spending, and inflation risks. September inflation data showed consumer prices rising 3.7% year over year, while wholesale prices accelerated, renewing concerns about Federal Reserve policy. Semiconductor stocks experienced substantial selling pressure, and uncertainty surrounding the financing of AI infrastructure weighed on growth-oriented investments. Meanwhile, higher oil prices amid Middle East tensions added to inflation concerns, encouraging investors to favor more defensive areas of the market.
Artificial Intelligence, Semiconductors, and Cloud Computing: Semiconductor investments experienced significant weakness, with the sector declining 10.53%, substantially underperforming the S&P 500 by 8.58 percentage points. Nvidia, Advanced Micro Devices, Broadcom, Micron Technology, and Intel faced selling pressure as investors questioned the sustainability of AI-related capital expenditures. Cloud computing and internet-related investments also encountered valuation concerns, affecting companies such as CoreWeave, Amazon, and Alphabet. Despite strong AI demand and encouraging semiconductor industry results, investors increasingly focused on financing costs, competitive pressures, and the timeline for realizing returns on AI infrastructure investments.
Cryptocurrency and Blockchain: Blockchain-related investments fell 13.88%, making them the weakest of the two highlighted thematic categories and underperforming the semiconductor sector by 3.35 percentage points and the S&P 500 by 11.93 percentage points. Bitcoin-related investments and cryptocurrency infrastructure companies faced pressure as investors reduced exposure to speculative growth assets. Companies such as Coinbase, Riot Platforms, and Marathon Digital Holdings illustrate the industry’s sensitivity to cryptocurrency prices, financing conditions, and risk appetite. The week’s broader technology sell-off reinforced concerns about volatility across highly speculative investment themes.
Leisure, Water Infrastructure, and Homebuilding: Leisure and entertainment gained 2.32%, outperforming the S&P 500 by 4.27 percentage points and leading the three strongest highlighted categories. Water infrastructure advanced 2.14%, while homebuilding rose 1.93%. Leisure-related companies, including booking and entertainment businesses, benefited from selective investor demand. Water infrastructure investments offered exposure to water treatment, distribution, and equipment providers, while homebuilders reflected changing expectations for housing demand and borrowing costs. These three areas demonstrated greater resilience than technology-oriented investments during the week’s market pullback.
Other Thematic Investments: Energy infrastructure and natural resources attracted attention as oil prices climbed above $100 per barrel. Gold-related investments benefited from safe-haven demand, while copper, uranium, clean energy, cybersecurity, biotechnology, robotics, and digital infrastructure remained sensitive to individual company developments and changing growth expectations. Diversification across these themes remains important because commodity exposure, interest-rate sensitivity, and company-specific risks can produce substantially different results.
Overall, markets experienced a pronounced rotation away from speculative technology investments toward selected defensive and economically sensitive industries. Investors will continue monitoring inflation, interest rates, corporate earnings, and AI spending for direction. In this environment, diversification and disciplined portfolio construction remain essential.