COMMENTARY:
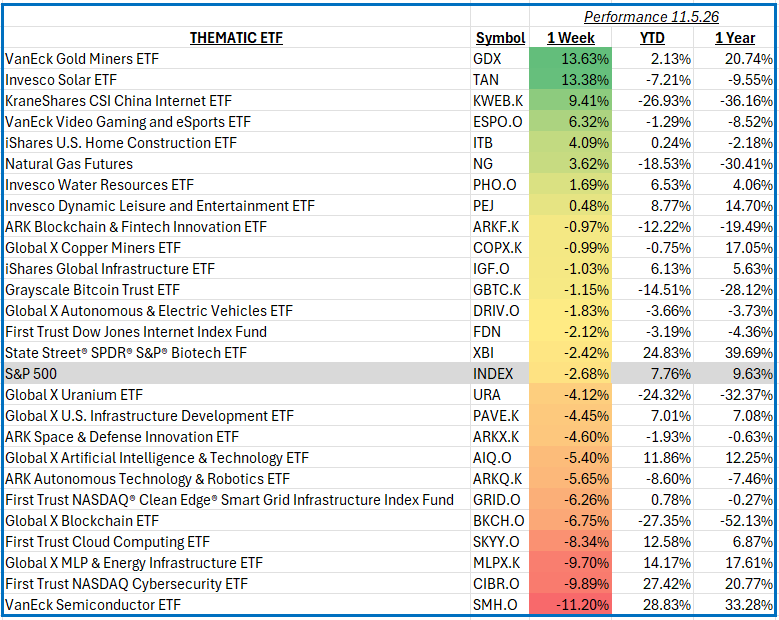
The S&P 500 declined 2.68% for the week ending November 5, 2026, as investors reassessed valuations across thematic equity investments, particularly artificial intelligence (AI), semiconductors, and data-center infrastructure. Democratic victories in the U.S. midterm elections raised concerns about potential restrictions on data-center development, while uncertainty surrounding future AI spending intensified selling in technology-related investments. Meanwhile, gold rallied as investors sought defensive assets, and expectations of progress toward resolving U.S.-Iran tensions contributed to a sharp decline in oil prices. These developments drove substantial performance differences across investment themes.
Precious Metals and Clean Energy: Gold mining stocks advanced as gold prices climbed above $4,100 per ounce amid geopolitical uncertainty and shifting interest-rate expectations. Newmont, Agnico Eagle Mines, and Barrick Mining were important companies to watch within the gold-mining theme. Solar energy investments also rallied, supported by renewed investor interest in clean energy following the elections. First Solar, Enphase Energy, and SolarEdge Technologies represent important companies in this area, although individual performance varied. The strong results highlighted investor rotation toward precious metals and selected renewable-energy businesses during a volatile week.
Chinese Internet and Digital Commerce: Chinese internet stocks gained as investors considered the implications of lower oil prices, improving global risk sentiment in some markets, and China’s economic outlook. Alibaba, Tencent, JD.com, and PDD Holdings were key companies influencing this investment theme. Lower energy costs could benefit China as a major oil importer, while investors continued evaluating consumer spending, online commerce, and digital advertising growth. Nevertheless, regulatory uncertainty and concerns about China’s economic recovery remained important considerations for investors.
Cybersecurity and Digital Infrastructure: Cybersecurity investments weakened as investors reduced exposure to technology-related growth themes. Companies such as CrowdStrike, Palo Alto Networks, Fortinet, and Cisco Systems were important constituents within the cybersecurity landscape. Meanwhile, semiconductor stocks suffered significant selling pressure as investors questioned whether AI-related capital expenditures could sustain their rapid growth. Nvidia, Broadcom, Advanced Micro Devices, and Taiwan Semiconductor Manufacturing were among the major companies influencing semiconductor performance. Concerns about data-center permitting and the profitability of AI infrastructure intensified the sector’s decline.
Relative Performance: Gold mining investments gained 13.63%, outperforming the S&P 500 by 16.31 percentage points and leading the thematic investments listed. Solar energy followed with a 13.38% advance, while Chinese internet stocks rose 9.41%. At the other extreme, semiconductor investments declined 11.20%, underperforming the broad market by 8.52 percentage points. Cybersecurity fell 9.89%, also reflecting the market’s retreat from technology-oriented growth investments.
Overall, the week demonstrated how political developments, commodity prices, and changing expectations for AI spending can produce sharply divergent thematic returns. Investors faced a challenging environment, with precious metals and selected clean-energy investments outperforming while semiconductor and cybersecurity themes struggled.