COMMENTARY:
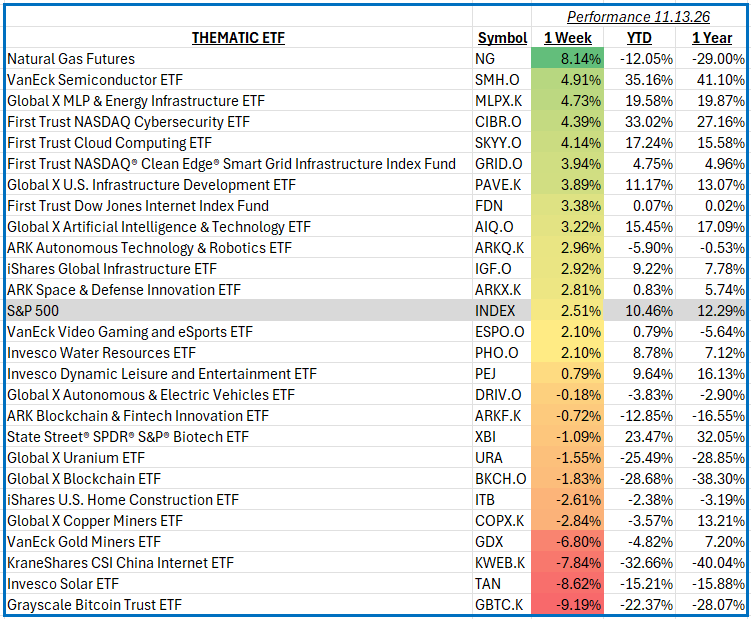
For the week ending November 13, the S&P 500 returned 2.51%, snapping a four-week losing streak. For thematic investors, the week showed how quickly leadership can shift: natural gas and energy infrastructure benefited from changing weather and energy demand, while chipmakers rallied even as concerns around artificial intelligence remained. Sticky inflation data also kept interest rates in focus, a risk for long-duration growth themes such as solar and digital assets.
Energy and infrastructure led the themes listed. Natural gas futures gained 8.14%, 5.63 percentage points ahead of the S&P 500, while energy infrastructure rose 4.73%. Colder weather forecasts, strong liquefied natural gas exports and a tighter-than-expected storage balance helped lift gas prices. Pipeline and processing companies such as Williams Companies and Enterprise Products Partners are key holdings in the infrastructure theme and can benefit from energy volumes and demand.
Semiconductors and artificial intelligence advanced 4.91%, 2.40 percentage points above the broad market. Advanced Micro Devices and Broadcom gained as investors rotated toward alternatives to Nvidia; both were among the week’s stronger chip stocks. Nvidia’s leadership shake-up and a sharp decline in its shares, however, renewed questions about AI investment and the market’s reliance on a handful of large technology companies. The result was a strong week for many chipmakers, but an uneven one for the AI theme overall.
Digital platforms, cybersecurity and connected technology also drew attention. Across themes such as cloud computing, internet platforms, gaming and cybersecurity, investors continued to balance long-term growth prospects against higher borrowing costs and questions about the returns on technology spending. The week’s sharp swings in chip stocks showed how news around a major company can quickly spill over into related growth themes.
Materials and strategic resources—including copper, uranium and gold—remain tied to demand for electrification, power generation and infrastructure. Those long-term drivers competed this week with short-term sensitivity to rates, inflation and commodity prices. Individual miners and materials companies can move differently from the underlying commodity, so the broader theme did not translate into uniform performance.
Clean energy and digital assets lagged. Solar fell 8.62%, 11.13 percentage points below the S&P 500, while Bitcoin fell 9.19%, 11.70 points below it and 0.57 points behind solar. Solar companies such as First Solar faced pressure amid concerns about financing costs and demand; Bitcoin’s decline coincided with sizable outflows from digital-asset investment products.
Markets finished higher, but thematic performance diverged sharply. Energy and chips led the week, while solar and Bitcoin struggled.